Skip to content

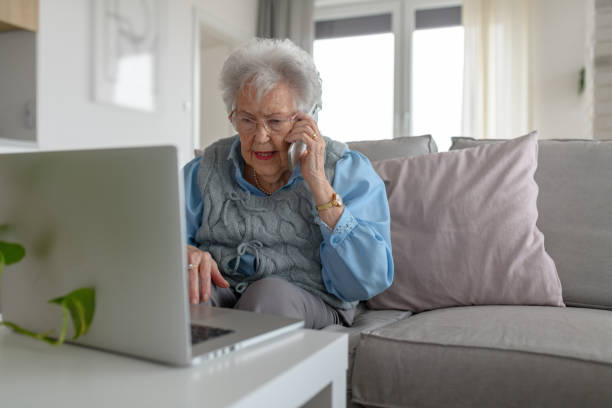
Your phone rings, and the caller ID appears to show the name of your bank.
The person on the other end knows your name. They know where you bank. They may even know the last four digits of your account.
Then they deliver the frightening news: “We’ve detected suspicious activity in your account.”
Your heart rate rises. Someone may have compromised your identity, and thousands of dollars could already be at risk. Fortunately, the caller says the bank’s fraud department caught the problem—and they are ready to help you protect your money.
There is only one problem.
They are not calling from your bank.
The person promising to protect your retirement savings is actually trying to steal them.
Financial scams do not only fool naïve people
Most of us believe we would recognize a scam. We are intelligent, experienced, and careful with money. We assume we would notice something suspicious before handing over personal information or transferring funds.
Unfortunately, financial scams do not succeed because their victims lack intelligence. They succeed because criminals manipulate people into making one bad decision at exactly the wrong moment.
According to the FBI, people over age 60 submitted more than 201,000 internet-crime complaints during 2025 and reported losses exceeding $7.7 billion. The average reported loss was more than $38,000, while at least 12,400 older victims reported losing $100,000 or more. Investment schemes alone accounted for more than $3.5 billion in reported losses among older victims. FBI: Scammers Target Older Adult Victims
These victims include business owners, executives, doctors, educators, engineers, professionals, parents, and grandparents. Many spent 30, 40, or even 50 years building their wealth.
That is precisely why they are attractive targets.
Scammers are attacking your decision-making
When we hear “cybercrime,” we may picture someone in a dark room hacking into a computer. Increasingly, however, criminals do not need to hack your computer.
They need to hack your decision-making.
Most successful impersonation scams use four psychological weapons:
- Fear: “Someone has accessed your account.”
- Urgency: “You must act before your money disappears.”
- Authority: “I’m calling from your bank or a government agency.”
- Isolation: “Don’t hang up or discuss this with anyone.”
Once those four elements come together, the victim is frightened, rushed, inclined to trust the caller, and prevented from consulting someone who might recognize the scam.
The victim does not believe money is being sent to a criminal. The victim believes the money is being protected from a criminal.
The Federal Trade Commission reports that combined losses among older adults who lost more than $100,000 to business and government impersonation scams increased eightfold between 2020 and 2024. FTC: False Alarm, Real Scam
Artificial intelligence makes scams more convincing
Technology has added another dangerous dimension to financial fraud.
In the traditional grandparent scam, someone calls claiming that a grandchild has been arrested, injured, or stranded. The situation is urgent, and money must be sent immediately.
In the past, an intended victim might recognize that the caller did not sound like the family member. Artificial intelligence can now help criminals imitate voices and produce convincing messages, images, and videos.
Information posted online can also reveal the names of family members, employers, hometowns, friends, and recent activities. Those details allow scammers to construct a story that feels personal and believable.
The FBI has warned that criminals are using AI-generated voices and other synthetic content to impersonate trusted individuals. Its central recommendation remains crucial: independently verify the identity of anyone requesting money or sensitive information. FBI guidance on malicious impersonation
Technology will continue to change. The need for a disciplined decision-making process will not.
Your retirement plan needs a fraud plan
Retirement planning usually includes an income strategy, investment allocation, Social Security decision, tax strategy, insurance review, and estate plan.
But what is your fraud plan?
What will you do if someone calls tomorrow and says $250,000 of your retirement account is in danger?
The worst time to create a response is while a stranger is frightening and pressuring you. Establish your response before the call arrives.
I call it the 24-Hour Retirement Security Rule:
When an unexpected caller, email, or text instructs you to transfer or withdraw money, purchase cryptocurrency, disclose a password, provide a verification code, or take another immediate financial action, stop.
Do not click the link. Do not transfer the money. Do not reveal the code. Do not allow the stranger to determine your timetable.
Hang up and independently contact the institution using a number printed on your statement, bank card, or official website. If an account might truly be compromised, contact the legitimate institution immediately—but do not move money based on the unexpected caller’s instructions.
Before making any substantial or unusual transaction, bring another trusted person into the conversation. That might be your spouse, child, financial professional, attorney, or another trusted family member.
A legitimate financial institution can survive your decision to verify the situation. A scammer cannot.
The power of postponing a financial decision
Throughout our working lives, we are rewarded for acting quickly, solving problems, and taking control. In retirement, wisdom sometimes requires the opposite response:
“I’m not making this decision right now.”
Those seven words can interrupt the scammer’s psychological strategy.
Remember the warning signs: fear, urgency, authority, and isolation. If someone demands immediate secrecy or financial action, treat that pressure as a reason to stop—not as a reason to comply.
Your retirement savings may represent decades of work, sacrifice, and disciplined decisions. Someone who contributed nothing toward building that security may attempt to steal it during a ten-minute telephone call.
Do not give that person those ten minutes.
Protecting retirement is not only about investment returns, Social Security, taxes, or Medicare. Sometimes it comes down to having the confidence to stop, verify, consult someone you trust, and only then decide.
If this information could protect someone you care about, please share it. One conversation today might cause someone to hang up on a scammer six months from now—and protect the retirement they spent a lifetime building.